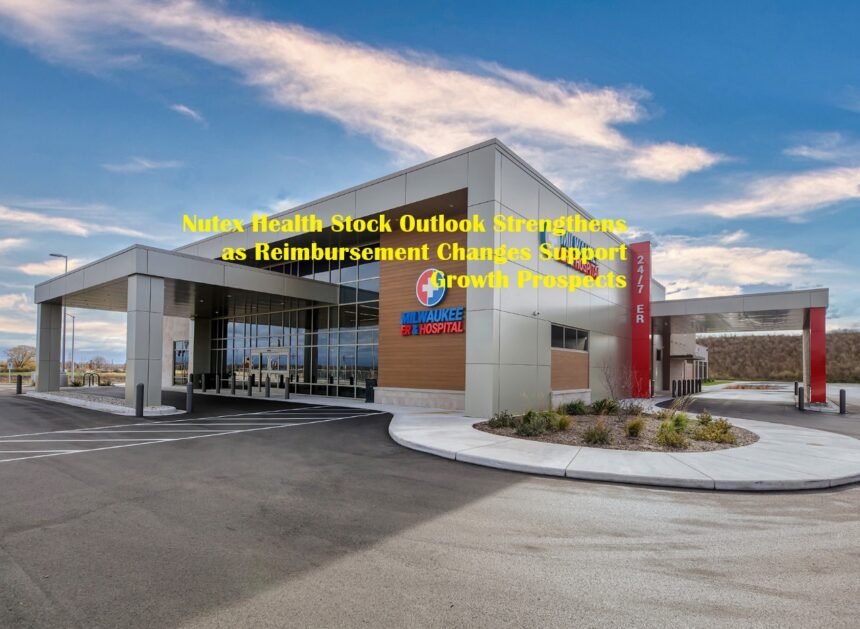
Nutex Health is drawing renewed attention from investors after Freedom Capital Markets increased its price target for the healthcare services company while maintaining its Buy rating. The revised target reflects the firm’s view that improving reimbursement conditions, strong hospital-level profitability, and a more predictable revenue environment could support the company’s next phase of expansion. Freedom Capital Markets raised its Nutex Health price target to $306 from $280, according to a September 25 analyst update.
The new target was based partly on management discussions following two days of investor meetings in the Midwest. Nutex management reportedly indicated that it does not see significant near-term headwinds and continues to regard second-quarter 2026 revenue as an appropriate baseline for future expectations. The development puts the spotlight on the factors that could influence the company’s operating performance beyond its recent stock-market momentum.
Reimbursement Outlook Becomes a Key Growth Factor
One of the most important elements behind Freedom Capital’s updated assessment is the changing reimbursement environment. Healthcare providers have faced uncertainty over payments and arbitration, making it more difficult for investors to estimate future revenue. According to the analyst commentary, management believes the reimbursement debate has shifted more favorably toward providers following the Fifth Circuit’s en banc decision in the TMA III case.
For Nutex Health, greater visibility around reimbursement could make its financial results easier to forecast. The company has historically operated in an environment where payment negotiations and arbitration could create fluctuations in revenue and expenses.
If regulatory developments reduce that volatility, investors may have greater confidence when assessing the company’s earnings potential. That does not eliminate the risks associated with reimbursement policy. Questions remain around payer responses, the durability of independent dispute resolution economics, and how revenue per patient visit will develop.
Hospital Economics Remain Central to the Investment Story
Nutex Health’s hospital operations represent another major component of the company’s financial profile. Freedom Capital highlighted hospital gross margins in the high-40% to low-50% range and EBITDA margins in the low-30% range. The analyst also pointed to average revenue of approximately $35 million and EBITDA of about $10 million per hospital.
Those figures indicate why the economics of individual facilities are important to the company’s broader growth strategy. Rather than measuring Nutex solely through its total revenue, investors can also examine how efficiently each hospital generates earnings. Strong unit-level economics could allow the company to expand its network while maintaining attractive profitability. The ability to reproduce those results across additional facilities will therefore remain an important consideration as Nutex continues its expansion plans.
Expansion Could Increase Revenue Capacity
Nutex Health has continued developing its healthcare network, giving the company another potential avenue for future revenue growth. The company’s operations include micro hospitals, specialty hospitals, hospital outpatient departments and population health services.
Its broader business model gives Nutex exposure to multiple areas of healthcare delivery rather than relying exclusively on a single type of facility. Recent company guidance has also called for three to five new hospital openings annually, with facilities planned in markets including Arkansas, Texas and Florida during the second half of 2026.
New facilities could increase the company’s revenue base, although expansion also requires capital, staffing and effective execution. The contribution from newly opened hospitals may therefore develop gradually rather than immediately matching established facilities.
NUTX Valuation Remains a Major Market Focus
The revised $306 price target is particularly notable because Nutex shares have already experienced substantial gains. The stock closed at $204.59 on September 24, meaning Freedom Capital’s target represented an implied upside of roughly 49.6% from that closing level. Nutex’s recent market performance has also attracted attention from other analysts.
Investing.com data showed an average 12-month analyst price target of $283, with Freedom Capital’s $306 target among the higher published targets. These targets represent analyst estimates rather than guaranteed future prices. Actual performance will depend on earnings, reimbursement developments, operating execution, market conditions and investor expectations.
Questions Investors Will Continue Watching
The next stage of Nutex Health’s story will depend on whether the company’s operational improvements can translate into sustainable financial growth. Investors are likely to monitor revenue per visit, new-hospital contributions, reimbursement trends and payer behavior. Management’s ability to maintain profitability while expanding its network will also remain important.
Another issue involves the durability of the independent dispute resolution framework. Although recent developments have improved the outlook described by management, changes in regulation or payer behavior could affect the economics of healthcare providers. Nutex also faces the challenge of maintaining its growth rate after a significant increase in its stock valuation.
What the New Price Target Signals
Freedom Capital Markets’ decision to raise its Nutex Health target from $280 to $306 reflects a more constructive assessment of the company’s growth and reimbursement outlook. The updated target places greater emphasis on predictable revenue, hospital profitability and the potential benefits of regulatory developments.
For investors following NUTX, the key issue is no longer simply the company’s recent share-price performance. The longer-term story will depend on whether Nutex can convert favorable reimbursement conditions and strong hospital economics into consistent earnings growth while successfully expanding its healthcare network.