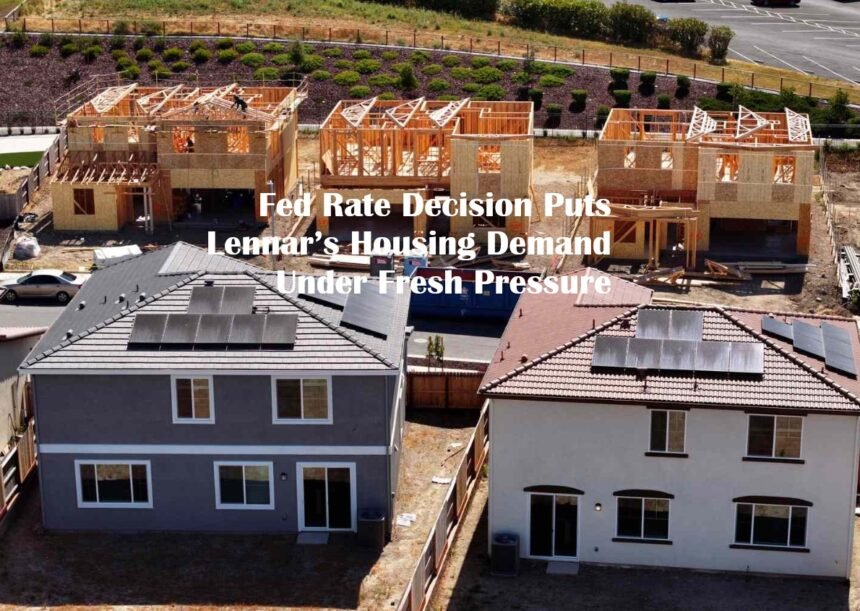
The U.S. housing market is entering another important test as the Federal Reserve prepares to announce its latest interest-rate decision, putting homebuilders under renewed scrutiny. Among the companies facing particular attention is Lennar, whose business is closely tied to mortgage affordability and consumer demand.
Markets have been positioning for a possible 25-basis-point rate increase at the September Federal Open Market Committee meeting. Recent market pricing had placed the probability of such a move in a high range, while the 30-year mortgage rate was already around 6.76% in the week ending September 11. For Lennar, the timing is especially significant because the company is scheduled to report fiscal third-quarter results after the market closes on September 16, shortly after the Fed’s decision and Chair Kevin Warsh’s press conference.
Mortgage Costs Remain the Central Issue
Higher interest rates affect homebuilders primarily through the affordability of monthly mortgage payments. Even when consumers remain interested in purchasing properties, elevated financing costs can force buyers to lower their budgets, delay purchases or demand financial incentives from builders.
Lennar has already been responding to this environment through mortgage-related incentives. During the quarter ended May 31, 2026, its sales incentives represented about 12.9% of deliveries, although that figure had declined from 14.1% in the previous quarter and 14.5% in the fourth quarter of 2025. These incentives can help maintain sales volumes, but they also affect profitability.
Lennars gross margin on home sales had fallen as the company worked to keep homes affordable in a challenging financing environment. That creates an important relationship between monetary policy and the company’s financial results mortgage rates influence affordability, affordability influences demand, and demand can determine how much discounting builders need to offer.
Lennar Heads Into Earnings With Several Variables
The Fed decision is not the only event investors are watching. Lennar’s earnings report arrives later the same day, creating an unusual sequence in which monetary policy will be known before the company’s quarterly figures become public. Analysts are expected to focus on several areas, including home deliveries, new orders, average selling prices and incentives.
Lennar delivered 20,519 homes during the quarter ended May 31 and reported 21,700 new orders. Its previous results also showed that the company continued to generate significant housing activity despite the difficult rate environment. The question now is whether that demand can remain durable if borrowing costs stay elevated.
Bond Yields Add Another Layer of Pressure
The housing equation is also being affected by longer-term Treasury yields. The 10-year Treasury yield was approaching 5% in the days leading into the Fed meeting, according to market reports. Meanwhile, the 30-year mortgage average had moved higher from 6.71% the previous week to 6.76%.
That distinction matters because mortgage rates do not simply move one-for-one with the Federal Reserve’s policy rate. Longer-term borrowing costs are influenced heavily by Treasury yields, mortgage-backed securities and expectations for future monetary policy.
Consequently, even if a rate increase is already reflected in financial markets, the Fed’s guidance could remain important for housing stocks.
What Investors Will Watch in Lennar’s Results
Lennar’s earnings release could provide a more detailed picture of how buyers are responding to the current financing environment. One key indicator will be incentives. A continued decline could suggest that the company is finding ways to maintain demand without increasing discounts. Conversely, renewed increases would indicate that affordability remains a significant obstacle.
New orders will also be closely watched because they provide a forward-looking indication of housing demand. Average selling prices can offer another signal about the balance between pricing power and affordability. The company’s financial position is another consideration. Lennar had approximately $1.8 billion in cash at the end of its second quarter, while homebuilding debt represented a relatively modest portion of its capital structure.
Housing Data Adds to the Picture
Additional housing data arriving shortly after the Fed decision could provide another important signal. Housing starts and building permits for August are scheduled for release on September 17, one day after the monetary-policy announcement. Together, these indicators can help investors distinguish between a temporary slowdown in housing activity and a broader deterioration in demand. For Lennar, the September 16 combination of the Fed decision and quarterly earnings therefore creates an unusually concentrated catalyst.
Mortgage rates, consumer affordability, incentives, orders and management’s outlook will all become important pieces of the same housing-market story. Rather than focusing solely on whether the Fed raises rates, the broader issue is how monetary policy translates into mortgage costs and ultimately into the willingness and ability of Americans to purchase new homes.