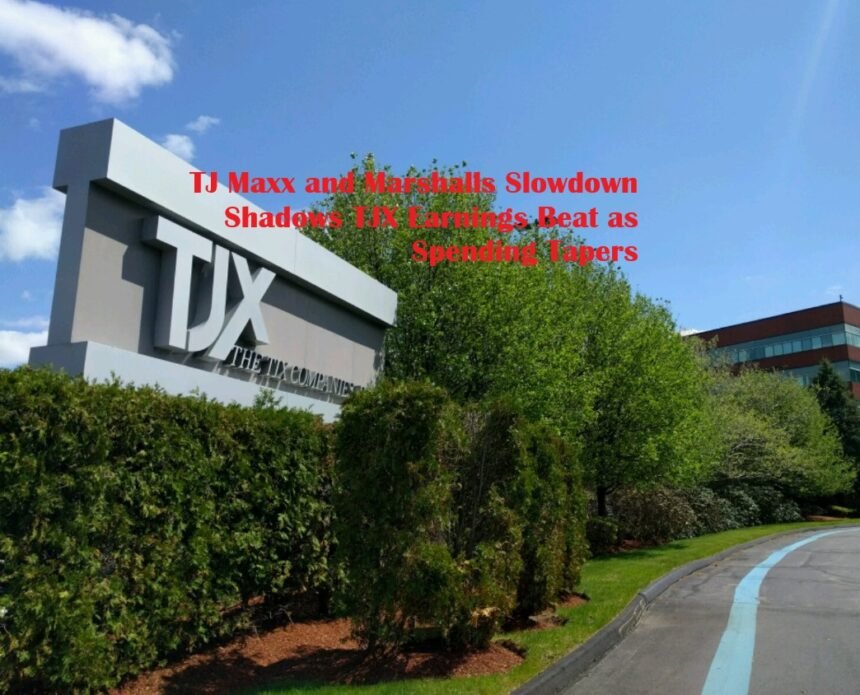
Off-price retail powerhouse TJX Companies posted strong second-quarter financial results on Wednesday, August 19, 2026, beating Wall Street earnings and revenue expectations. However, an abrupt growth deceleration across its core TJ Maxx and Marshalls stores overshadowed the overall performance, sparking fresh investor concerns regarding American consumer health.
While budget-conscious shoppers continue hunting for value, the company’s apparel-focused Marmaxx division registered noticeable headwinds right before critical back-to-school and holiday shopping periods. The sudden operational deceleration caused company shares to dip in early morning trading despite an elevated full-year profit forecast.
Marmaxx Apparel Growth Decelerates sharply Across US Locations
Marmaxx represents TJX’s largest operational business unit, encompassing thousands of TJ Maxx and Marshalls storefronts nationwide. The division generated just 1% comparable store sales growth during the second quarter, marking a sharp drop from the robust 6% rate posted in the previous quarter.
Retail analysts attribute the Marmaxx slowdown to a combination of internal pricing recalibrations and broader consumer fatigue. Inflationary pressures over the past eighteen months forced subtle price increases across clothing lines, prompting cost-sensitive shoppers to reduce the total number of items per store visit.
This deceleration highlights how middle-income and low-income households are prioritizing essentials while curbing discretionary apparel spending. Although store foot traffic remains positive, smaller basket sizes per customer transaction directly restrained overall revenue potential.
- Basket Size Reduction: Shoppers bought fewer discretionary items per checkout interaction.
- Price Sensitivity: Cumulative merchandise price hikes over recent years generated buyer resistance.
- Apparel Headwinds: Clothing categories underperformed compared to non-apparel retail segments.
- Market Competition: Value rivals like Ross Stores and Burlington continue contesting market share.
Non-Apparel and International Segments Offset Domestic Weakness
Despite headwinds across domestic clothing chains, TJX benefited immensely from its diversified international retail portfolio. The company’s HomeGoods banner, alongside its Canadian and European divisions, delivered robust comparable sales gains between 6% and 7%.
Strong performance in home furnishings and international markets cushioned the parent firm from deeper domestic pullbacks. Home Goods benefited from renewed consumer interest in affordable home decor upgrades, proving that discount shoppers still allocate funds toward non-clothing categories.
- Home decor Rebound: Consumers prioritized home furnishings over apparel upgrades.
- Global Resilience: Overseas branches in Canada and Europe outpaced American retail stores.
- Balanced Portfolio: Diversified store banners protected overall corporate profitability.
- Promotional Push: Enhanced marketing campaigns helped sustain steady store visitation rates.
Tariff Refunds Bolster Balance Sheet and Guidance Outlook
A major financial catalyst during the quarter involved substantial customs tariff refunds. TJX collected approximately $331 million in aggregate refunds for previously paid import tariffs under emergency trade acts. These lump-sum cash injections provided significant support to second-quarter net income.
Management raised its full-year fiscal 2027 earnings per share expectations to a range of $5.31 to $5.36, up from its earlier guidance of $5.08 to $5.15. However, third-quarter profit projections excluding tariff benefits came in slightly below analyst consensus, keeping investors cautious about core operational margins.
- Tariff Cash Inflow: $331 million in refunds expanded overall net quarterly profitability.
- Upgraded EPS Outlook: Management raised full-year profit projections substantially.
- Conservative Q3 Targets: Future quarter operational targets account for rising labor costs.
- Stable Sales Projection: Full-year comparable store sales growth targets remain firm at 3% to 4%.
Navigating Competitive Dynamics and Shifting Consumer Habits
The off-price retail sector faces a rapidly changing macroeconomic landscape shaped by trade policy shifts, labor cost pressures, and changing buyer behavior. Budget-conscious consumers are exercising extreme selectivity, comparing deal quality across multiple off-price chains before making purchases.
TJX leadership remains confident that its flexible buying model will allow executives to acquire high-quality name-brand inventory at heavy discounts. The company continues adjusting promotional strategies and store merchandising to reactivate shopper interest across its flagship apparel stores.
- Flexible Sourcing: Off-price buyers capitalize on excess vendor inventory liquidations.
- Targeted Promotion: Customized marketing campaigns focus on high-value brand deals.
- Cost Discipline: Store managers control operating expenses to preserve profit margins.
- Assortment Adjustments: Merchandisers reallocate shelf space toward high-performing product categories.
Long-Term Outlook for Off-Price Retail Operations
TJX’s mixed second-quarter performance illustrates the complex environment facing off-price retailers today. While the company’s diversified model, home goods growth, and tariff windfalls delivered an impressive profit beat, revitalizing the core apparel segment remains crucial.
As the retail industry enters the crucial autumn and holiday shopping windows, corporate management must balance pricing discipline with value perception. Realigning apparel merchandise to match consumer budgets will determine whether TJ Maxx and Marshalls can reclaim their former growth momentum.