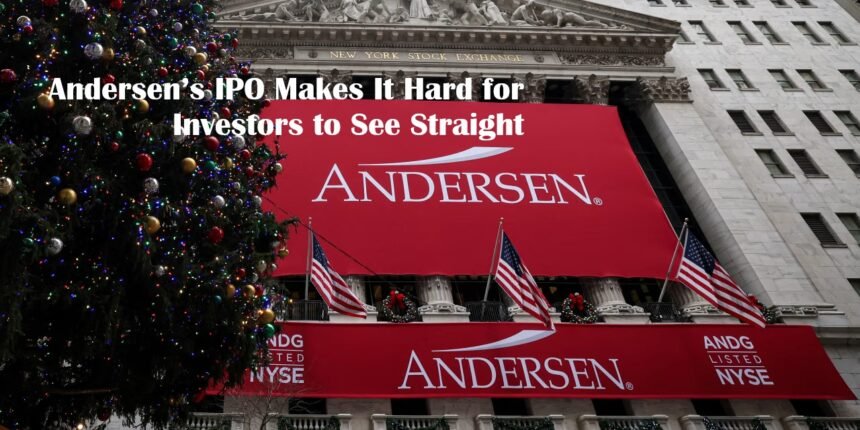
Andersen Group’s initial public offering debuted with strong stock performance, but many investors are struggling to interpret the company’s structure and financial reality. The professional‑services firm, rooted in the legacy of a former accounting giant, entered public markets after decades of private operations.
Its IPO was priced at $16 per share and drew notable enthusiasm from the investing community. However, beneath the surface of the stock’s early rally lies a corporate design that complicates value assessment for everyday shareholders. The firm’s IPO reflects a striking contrast, bold investor demand on one hand and structural concerns on the other.
This duality has created a situation where market enthusiasm may obscure deeper issues. Investors who glance only at the post‑IPO stock gains may miss important details about how Andersen is structured and what wealth truly belongs to public owners.
A Legacy Reimagined: Andersen’s Path to Public Markets
Andersen Group traces its modern origins to the aftermath of a historical accounting firm’s collapse. After the original brand faced legal and reputational turmoil decades ago, partners eventually revived the name under a new corporate identity. The revived Andersen Group has focused on tax, accounting, and advisory services rather than traditional audit work.
This distinct focus differentiates it from its predecessor while maintaining an iconic brand legacy. The decision to go public came after years of expansion. The company’s leadership saw an opportunity to raise capital and enhance visibility by accessing public markets.
Its IPO took place in December, offering shares to investors under conditions that mixed optimism with complexity. The early trading results showed strong price movement, but that has raised more questions than answers for some market participants.
Corporate Structure: A Maze for Public Shareholders
One of the most challenging aspects for investors is Andersen’s corporate structure. The public company controls only a modest share of the business while insiders retain decisive control through voting rights and financial claims. Public investors own a relatively small stake, while insiders hold nearly all voting power.
This arrangement gives founders and early partners significant influence over governance and long‑term decisions. The corporate design also includes a so‑called Up‑C structure, a financial arrangement often used in public listings that involves partnerships. This structure allows existing partners to exchange partnership units for shares while retaining certain tax benefits.
In Andersen’s case, most tax savings and future cash flow benefits are directed to insiders through a long‑term agreement. Public shareholders receive less of the financial upside than they might expect from the revenue figures alone. Because the company consolidates all operating revenue on its balance sheet, the top‑line figures may appear robust.
However, only a fraction belongs to the publicly traded entity. Most of the revenue and profits flow through to private holders. As a result, the income statement can seem misleading for anyone who does not study the fine print carefully.
Financial Performance: Reading Between the Lines
Andersen reported substantial revenue over the past twelve months, giving it an appearance of scale. Yet when profits are adjusted to reflect real public ownership, the picture changes. The company’s net loss on a pro forma basis highlights how one‑time costs and restructuring related to the IPO have impacted reported results.
Many of the financial gains that show up in consolidated figures do not translate directly to public shareholder value. These results make it essential for investors to look beyond headline numbers. The revenue is real, but its allocation across entities and ownership layers affects how much of that revenue benefits public holders. Ignoring these details can lead to overly optimistic valuations.
Internal Controls and Irony in Disclosure
Another notable issue uncovered in the IPO disclosures was a weakness in internal financial controls. Andersen acknowledged that it lacked the robust systems necessary for public reporting. The irony is striking, the company offers advice on internal control design to clients, yet its own disclosures reveal deficiencies.
This admission raised eyebrows, given the firm’s reputation and advisory expertise. Management has pledged to correct these weaknesses, but the initial disclosure highlights a gap that could matter to risk‑conscious investors.
Firms with sound internal mechanisms typically inspire more confidence among public owners, and this issue has become part of the broader conversation around Andersen’s IPO.
Market Reaction and Investor Sentiment
Despite structural concerns, the stock has performed well in its early days of trading. Andersen’s shares opened above the IPO price and rallied, signaling that demand for the company’s stock remains high. This surge reflects investor enthusiasm for growth opportunities in tax and advisory services.
It also suggests broader confidence in firms that blend legacy expertise with modern business models. At the same time, the stock’s rise complicates value analysis.
Traders who bought early may benefit from short‑term price moves, but long‑term investors need clarity about fundamentals. The interplay between market sentiment and detailed structural factors defines the current investor debate.
Competitive and Technological Risks Ahead
Beyond structural complexity, Andersen faces market risks like any public professional‑services firm. The industry is not immune to technological disruption. Automation and artificial intelligence are reshaping how tax, accounting, and advisory services are delivered. The company’s reliance on hourly billing could be challenged as technology improves efficiency.
If clients adopt AI tools for tasks traditionally billed at hourly rates, revenue could face pressure. Management insists the firm is investing in technology and AI integration to remain competitive. Still, the pace of change in clients’ expectations and competitive offerings poses uncertainty. Investors must weigh these future risks alongside current valuation metrics.
Why Andersen’s IPO Matters
This IPO is significant for several reasons. It marks a return to public markets for a firm connected to a storied name in accounting history. It also highlights how modern corporate structures can influence investor outcomes.
Rather than a simple public offering of equity tied to straightforward earnings, Andersen’s listing brings a layered financial design that rewards insiders differently from public holders. For the broader market, Andersen’s experience underscores the importance of due diligence.
Investors must go beyond surface numbers and understand how revenue, ownership rights, and financial arrangements affect value. In the current environment, where structural innovation and strategic financing intersect, clarity becomes a critical asset for shareholders.